What China’s Expectations of Personalised Luxury Service Mean for Brands
The Chinese source cites a figure from Deloitte's 2026 Global Powers of Luxury Goods report: 69.5% of Chinese consumers expect personalised products and services. Above the cited global average, it points to the importance of recognition, relevant preferences and continuity between digital and physical experiences.
The useful question is why those expectations are especially strong in China.
A more experienced luxury customer
Over two decades, customers have seen the market develop from early store openings to global launches. Interest has broadened from visible logos to materials, craftsmanship and provenance, while social reviews increasingly inform choices.
The source describes a shift from asking what is most popular to asking what is most suitable. Personalisation therefore needs to help customers navigate products and services, not simply offer more options.
Data needs to produce a better experience
The article interprets the demand for personalisation as an opportunity for a value exchange: customers provide relevant information and expect the brand to use it well.
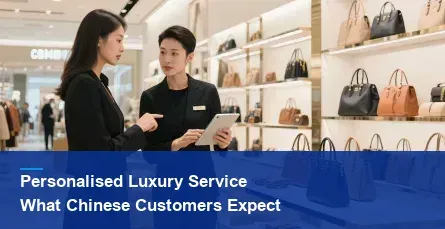
An advisor might access authorised purchase history, size or colour preferences and recent interests. A mini-program enquiry can inform preparation for a later store visit. Recognition should remain consistent across the website, store, channels for private-domain customer engagement and advisor interactions.
A CRM member centre can connect profiles, tags, service records and benefits. The purpose is to make information useful during service rather than leave it scattered across touchpoints.
Connect the whole journey
Chinese consumers are accustomed to moving between content, shopping, stores, mini-programs and service without treating each as a separate relationship. A store trial may lead to an order at home; an online purchase may require a digital return appointment.
Fragmentation becomes visible when one touchpoint cannot continue what another started. Luxury brands therefore need to evaluate the entire journey, with retail systems connecting sales, identity, inventory and advisor service to the digital relationship.
Three requirements for meaningful personalisation
Data: connect relevant browsing, enquiries, purchases, visits and after-sales records into a usable customer view. Information that does not improve service can weaken the expected value exchange.
Experience: make recognition consistent in online browsing, store trials and customer-service conversations. Personalisation should reach beyond advertising.
Brand understanding: experienced customers also want to understand craftsmanship, value and why a product deserves their time and attention. Better targeting cannot replace a credible brand story.
PEKON's experience with premium retail reflects a move from asking whether a digital capability exists towards asking how deeply it supports customer understanding and continuity.
What this means for growth in China
The source interprets the 69.5% figure as part of a broader shift from network and traffic expansion towards the quality of individual relationships. Brands need to understand not only what a customer bought, but why, in what context and what may be useful next.
This requires stronger connections among customer information, store service, membership and brand communication. More customisation choices alone do not establish that capability.
Source note: based on the Chinese article's interpretation of the regional-market discussion in Deloitte's 2026 Global Powers of Luxury Goods report.
Frequently asked questions
What does personalised luxury service include?
Product customisation, preference recognition, dedicated advice, connected journeys, membership benefits, use of relevant purchase history and tailored recommendations.
Why are expectations high in China?
The source links them to experienced luxury customers and a highly digital shopping environment where convenience, responsiveness and continuity are already familiar.